Form 1099-NEC reports nonemployee compensation: what a business paid independent contractors, freelancers and other non-employees for services during the year. The 2026 version is the biggest update since the form returned in 2020, with a much higher filing threshold and new boxes for tips and overtime.
This guide covers what changed for 2026, who has to file, what goes in each box, the deadlines and penalties and what contractors should do with the form once it arrives.
What's New on Form 1099-NEC for 2026
- $2,000 threshold: for payments made after December 31, 2025, you file a 1099-NEC when you pay a nonemployee $2,000 or more in a year, up from $600. The amount may be adjusted for inflation starting in 2027.
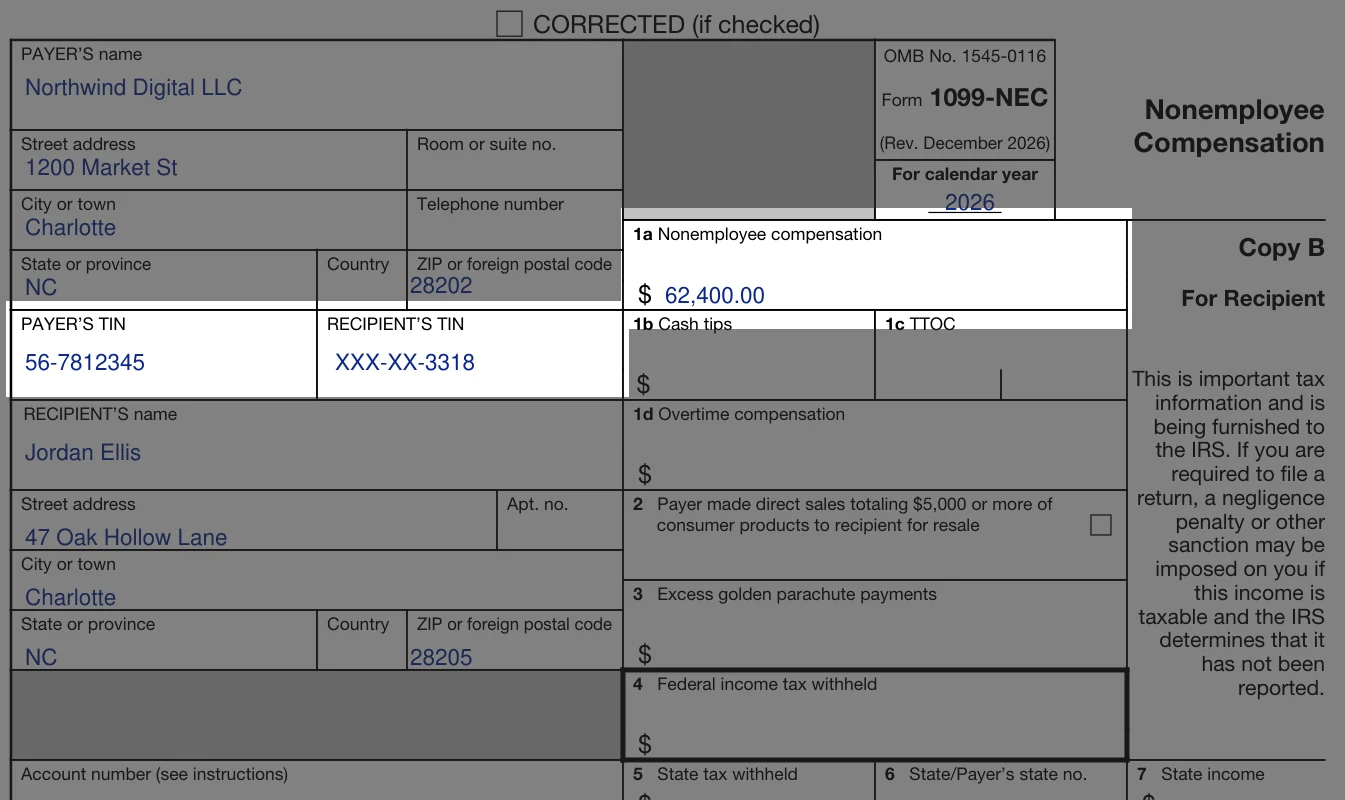
- Box 1 split into 1a to 1d: 1a is nonemployee compensation, 1b is cash tips, 1c is the Treasury tipped occupation code (TTOC) and 1d is overtime compensation.
- Deadline: 2026 forms are due February 1, 2027, because January 31 falls on a Sunday.
- Backup withholding: the same $2,000 threshold now applies when deciding whether backup withholding is required.
These changes come from the 2025 tax law and are set out in the IRS instructions for Forms 1099-MISC and 1099-NEC.
Who Must File Form 1099-NEC
You must file a 1099-NEC for each person you paid at least $2,000 during 2026 if all of the following are true:
- The payment was for services performed by someone who is not your employee.
- You paid it in the course of your trade or business, not as a personal expense.
- You paid an individual, a partnership, an estate or, in certain cases, a corporation.
Payments to corporations are generally exempt, with an important exception: fees paid to attorneys for legal services are reported regardless of whether the law firm is incorporated. Payments you made by credit card, debit card or through a payment app are not reported on a 1099-NEC, because the card processor or app reports them on Form 1099-K instead.
Collect a Form W-9 before the first payment so you have the contractor's legal name and taxpayer identification number (TIN). Without a valid TIN, backup withholding at 24% may apply.
Form 1099-NEC Box by Box
| Box | What goes in it |
|---|---|
| Payer and recipient | Names, addresses and TINs. The recipient TIN comes from the contractor's W-9. |
| 1a Nonemployee compensation | Total fees, commissions, prizes and awards for services paid to the contractor during the year |
| 1b Cash tips | Tips paid in cash or charged by customers that you report for the recipient. New for 2026. |
| 1c TTOC | Up to two Treasury tipped occupation codes for the recipient's tipped occupations. New for 2026. |
| 1d Overtime compensation | Overtime pay above the regular rate required under the Fair Labor Standards Act, when reportable on this form. New for 2026. |
| 2 Direct sales | Check if you sold $5,000 or more of consumer products to the recipient for resale |
| 3 Excess golden parachute payments | Excess parachute payments, when applicable |
| 4 Federal income tax withheld | Backup withholding, if any |
| 5 to 7 State information | State tax withheld, state and payer state number and state income, where required |
How to Fill Out and File Form 1099-NEC
- Confirm who needs a form. Total each contractor's 2026 payments made by cash, check or bank transfer and flag anyone at $2,000 or more.
- Check the W-9 details. Match names and TINs before filing. A mismatch can trigger backup withholding notices later.
- Complete the form. Enter payer and recipient information, the total in Box 1a and any tips, occupation codes or overtime in Boxes 1b to 1d.
- Furnish Copy B to the contractor. Mail it or deliver it electronically if the contractor agreed to electronic delivery, by February 1, 2027.
- File Copy A with the IRS. Filers with 10 or more information returns of all types combined must e-file. Paper filers send Copy A with Form 1096.
- File with your state if required. Many states require their own copy or participate in the Combined Federal/State Filing program.
Deadlines and Penalties
| Item | 2026 forms |
|---|---|
| Copy B to recipients | February 1, 2027 |
| Copy A to the IRS, paper or electronic | February 1, 2027 |
| Penalty per late return, up to 30 days late | $60 |
| 31 days late through August 1 | $130 |
| After August 1 or never filed | $340 |
| Intentional disregard | $680, with no annual cap |
The penalty amounts shown are the IRS figures for returns due in 2026 and are adjusted for inflation each year. Penalties apply separately to late filing with the IRS and to late furnishing to the recipient.
1099-NEC vs. 1099-MISC and W-2
Nonemployee pay for services always goes on the 1099-NEC. Rents, royalties, prizes that are not for services, medical payments and attorney gross proceeds go on Form 1099-MISC. Wages paid to employees go on a Form W-2, with income tax, Social Security and Medicare withheld.
The label on a contract does not decide which form applies. If you control how, when and where the work is done, the worker may be an employee and misclassification can bring back taxes and penalties.
If You Receive a 1099-NEC
A 1099-NEC means the payer treated you as self-employed. Nothing was withheld, so you handle the tax yourself:
- Report the income and your business expenses on Schedule C.
- Pay self-employment tax of 15.3% (12.4% Social Security and 2.9% Medicare) once net earnings reach $400.
- Make quarterly estimated payments by April 15, June 15, September 15 and January 15 if you expect to owe $1,000 or more.
- Report all self-employment income even if no 1099-NEC arrives, for example because a client paid you less than $2,000.
Landlords and lenders rarely accept a 1099 alone as proof of current income. Monthly pay stubs for independent contractors that match your deposits fill that gap and make it easy to check the 1099-NEC total when it arrives.
Missing or Incorrect 1099-NEC
If a client paid you $2,000 or more and no form has arrived by early February, ask the client for it. If the amount or TIN is wrong, ask for a corrected form rather than changing the numbers yourself. You can still file on time using your own invoices and bank records, because the income is taxable whether or not a form arrives.
Paid as a contractor? Keep monthly pay records that match your 1099-NEC.
Create a Pay Stub Now