Updated October 7, 2026 · Checked against the December 2026 IRS instructions for Forms 1099-MISC and 1099-NEC
Which Payments Go on a 1099-MISC
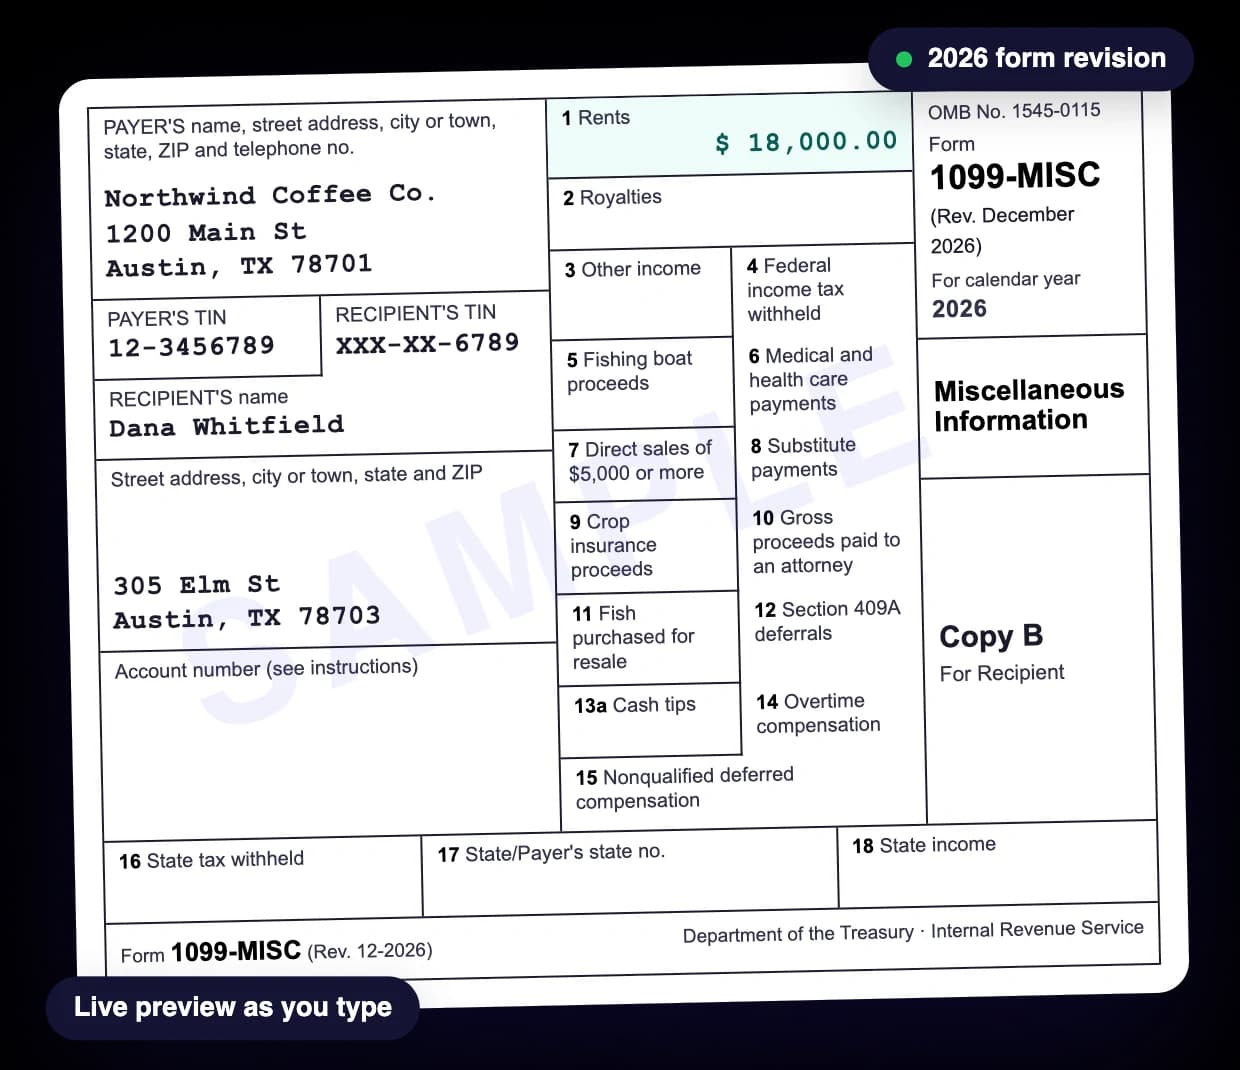
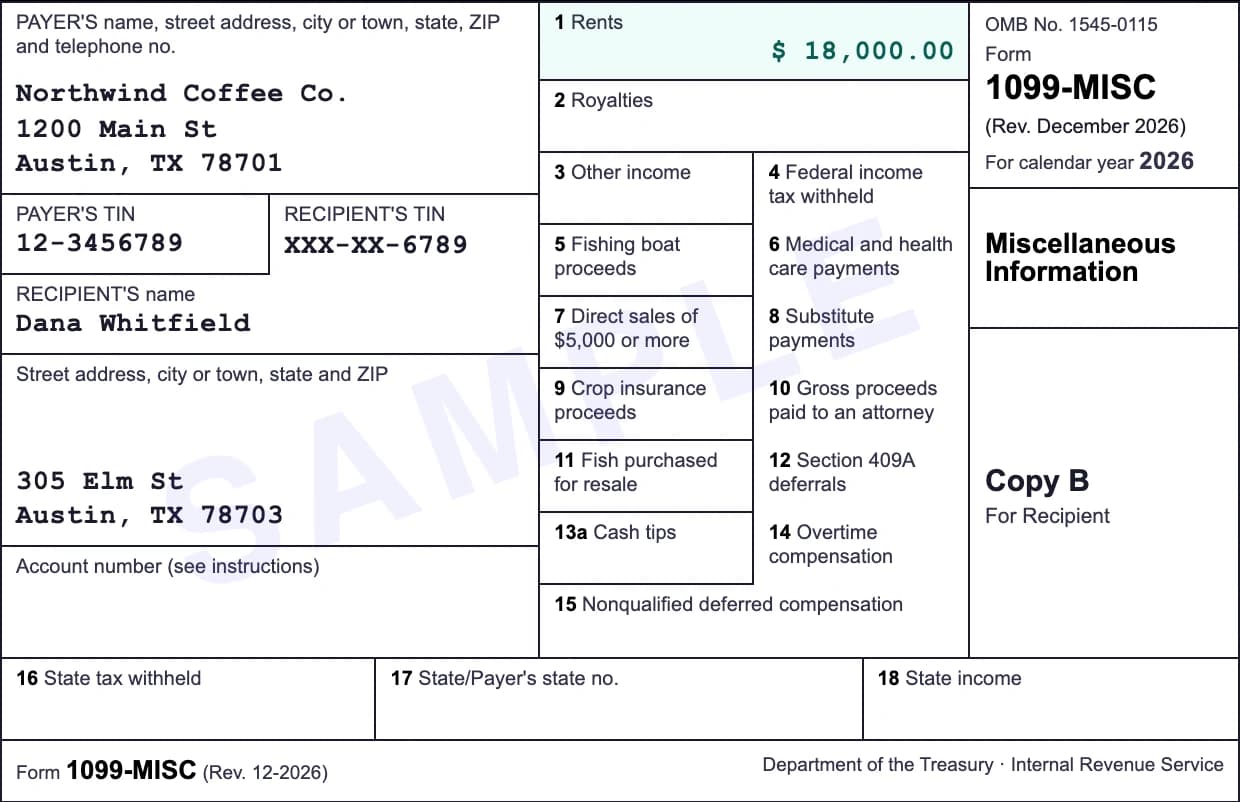
Form 1099-MISC, Miscellaneous Information, reports payments a business makes that are neither wages nor pay for services. Each kind of payment has its own box and its own reporting threshold for 2026.
1099-MISC boxes and 2026 thresholds| Box | What you paid | Report when it reaches |
|---|
| 1 | Rents for office space, equipment or land | $2,000 |
|---|
| 2 | Royalties | $10 |
|---|
| 3 | Prizes, awards and other income | $2,000 |
|---|
| 4 | Federal income tax withheld (backup withholding) | Any amount |
|---|
| 5 | Fishing boat proceeds | Any amount |
|---|
| 6 | Medical and health care payments | $2,000 |
|---|
| 7 | Direct sales of consumer products for resale (checkbox) | $5,000 |
|---|
| 8 | Substitute payments in lieu of dividends or interest | $10 |
|---|
| 9 | Crop insurance proceeds | $2,000 |
|---|
| 10 | Gross proceeds paid to an attorney | $600 |
|---|
| 11 | Fish purchased for resale | See instructions |
|---|
| 12 and 15 | Section 409A deferrals and nonqualified deferred compensation | $2,000 |
|---|
| 13a, 13b and 14 | Cash tips, tipped occupation code and overtime compensation | New for 2026 |
|---|
| 16 to 18 | State tax withheld, state number and state income | Optional |
|---|
The $2,000 figures applied from January 1, 2026. For payments made in 2025 those boxes used $600. The full rules are in the IRS Instructions for Forms 1099-MISC and 1099-NEC.
Who Files a 1099-MISC in 2026
A business, nonprofit or government agency files the form for each person it paid at or above the threshold in the course of its trade or business. Add up the year's payments to each recipient.
- Not reported: personal payments, such as the rent on your own home.
- Not reported: most payments to C and S corporations. Medical payments and attorney proceeds are the main exceptions and are reported even when the payee is a corporation.
- Not reported by you: rent paid to a real estate agent or property manager and anything paid by credit card or payment app, which the processor reports on Form 1099-K.
- Always reported: any payment from which you withheld federal income tax under the backup withholding rules.
1099-MISC vs 1099-NEC
Use the 1099-MISC for- Rent paid to a landlord
- Prizes, awards and settlements
- Royalties
- Medical and health care payments
- Gross proceeds paid to an attorney
Use the 1099-NEC for- Fees paid to freelancers and contractors
- Commissions paid to nonemployees
- Fees for an attorney's services
- Excess golden parachute payments
Nonemployee compensation left Box 7 of the 1099-MISC in 2020. Many small businesses need both forms at year end: one for the landlord, one for each contractor. Create the second with the 1099-NEC generator. Employees get neither; their wages go on a W-2 from the W-2 form generator.
1099-MISC Deadlines and Penalties
Unlike the 1099-NEC, the 1099-MISC has separate dates for the recipient copy, paper filing and e-filing.
1099-MISC due dates| What is due | Tax year 2025 | Tax year 2026 |
|---|
| Copy B to the recipient | February 2, 2026 | February 1, 2027 |
|---|
| Copy B when Box 8 or Box 10 has an amount | February 17, 2026 | February 16, 2027 |
|---|
| Copy A to the IRS on paper | March 2, 2026 | March 1, 2027 |
|---|
| E-file with the IRS | March 31, 2026 | March 31, 2027 |
|---|
Penalty per late or incorrect form| When it is filed correctly | Returns due in 2026 | Returns due in 2027 |
|---|
| Within 30 days of the due date | $60 | $60 |
|---|
| After 30 days but by August 1 | $130 | $130 |
|---|
| After August 1 or never | $340 | $340 |
|---|
| Intentional disregard | At least $680 | At least $690 |
|---|
Payers with 10 or more information returns in a year must e-file. After January 1, 2027 the free IRS IRIS system is the only way to do that. The 2027 dates follow the IRS weekend and holiday rule.
Common 1099-MISC Mistakes
- Putting contractor pay on the MISC. Fees for services belong in Box 1a of the 1099-NEC.
- Reporting personal payments. Only payments made in the course of a trade or business are reportable.
- Wrong TIN. Take the recipient's name and TIN from their signed Form W-9. The preview shows both TINs as they will print.
- Using the old $600 threshold. Rent, prizes and medical payments made in 2026 are reported from $2,000.
- Mixing up the two attorney boxes. Fees for legal services go on the 1099-NEC. Gross proceeds such as a settlement go in Box 10 here.
Using Your 1099-MISC Correctly
Online Paystub formats your payment records on the 1099-MISC layout. It does not file anything with the government. Give Copy B to the recipient and keep a copy for at least three years.
Copy A for the IRS is a scannable red form. The IRS says self-printed copies of Copy A cannot be scanned and may draw a penalty, so e-file or use the official printed form with Form 1096. A 1099-MISC must reflect payments that were actually made; creating one with invented income is fraud.