A payroll card, also called a pay card, is a reloadable prepaid card that an employer uses to pay wages electronically. Instead of a paper check or a deposit into your checking account, your net pay is loaded onto the card every payday and you spend it, withdraw it or transfer it from there.
Payroll cards can be a practical option if you do not have a bank account, but fees and withdrawal rules vary widely between programs. This guide explains how the cards work, how they compare with direct deposit, the protections you have under federal law, how to avoid fees and why you still need a pay stub when you are paid on a card.
How Does a Payroll Card Work?
- Payroll runs as usual. Your employer calculates gross pay, withholds taxes and subtracts benefits or other deductions.
- Net pay is loaded onto the card. On payday the remaining net pay is deposited into the prepaid account linked to your card.
- You use the balance. The card usually runs on the Visa or Mastercard network, so you can pay in stores, shop online, withdraw cash or pay bills.
- The cycle repeats. Each paycheck adds to the balance. You spend money that is already on the card rather than borrowing it.
The card is issued by a bank or card program manager, not by your employer. That company holds the funds, processes transactions and sets the fee schedule, which is why two employers' payroll cards can work very differently.
Payroll Card vs. Direct Deposit, Debit Card and Paper Check
| Feature | Payroll card | Direct deposit | Paper check |
|---|---|---|---|
| Bank account needed | No | Yes or your own prepaid account | No, but cashing it can cost money |
| Where the money goes | Prepaid account chosen by the employer's program | Account you choose | You deposit or cash it |
| Access to funds | Card purchases, ATMs, transfers | Your bank's debit card, transfers, checks | After depositing or cashing |
| Typical costs | Program fees, such as out-of-network ATM fees | Your bank's account fees | Check-cashing fees if unbanked |
| Risk if lost | Card can be blocked and replaced | Low | A lost check has to be stopped and reissued |
A payroll card looks like a debit card, but a debit card is tied to a checking account you opened, while a payroll card is tied to a prepaid account set up for your wages. It is also different from a general-purpose prepaid card you buy in a store, because wages are its main source of funds and it carries specific payroll card protections.
Compared with a paper check, a card removes the trip to the bank and any check-cashing fee. Checks also carry their own timing issues, since paychecks can go stale if they sit uncashed for months.
Can Your Employer Require a Payroll Card?
No. Under federal rules your employer cannot make a payroll card the only way to receive your wages. According to the CFPB, an employer that offers a payroll card must give you at least one other option and let you choose, such as direct deposit to an account of your choice or a paper check.
Some states go further and limit fees or require at least one free way to withdraw your full pay. If you are handed a payroll card without being offered a choice, ask payroll in writing for direct deposit or a check instead.
Payroll Card Fees and How to Avoid Them
Before you sign up, the card provider must give you a short-form disclosure with the key fees and a long-form list of every fee. Common charges include:
- Out-of-network ATM withdrawals and ATM balance inquiries
- Replacement cards
- Inactivity after a set number of months
- Foreign transaction fees
- Expedited or external bank transfers
- Paper statements or live-agent calls in some programs
How to keep fees near zero
- Use in-network ATMs and check your balance in the free app instead of at an ATM
- Ask for cash back with a purchase at a grocery or drug store
- Look for a free teller withdrawal at a partner bank to take out your full pay
- Move the balance to your own account with a free transfer, if the program offers one
- Keep the card active so an inactivity fee never kicks in
Getting Your Money Out
ATM withdrawals
Most cards work at ATMs on their network, but daily withdrawal limits may stop you from taking out a whole paycheck at once. A bank teller withdrawal or cash back at a register can fill the gap.
Transfers to a bank account
Many programs let you send money to a checking account using its routing and account numbers. Transfer times and fees vary, so check the app before relying on it for rent day.
Online purchases and bills
Cards on a major network work for online shopping and bill payments. Hotels, gas pumps and car rentals may place a temporary hold that reduces your available balance until it drops off, the same way pending transactions on a credit card work.
Are Payroll Cards Safe?
Payroll cards are covered by Regulation E under the Electronic Fund Transfer Act. That gives you fee disclosures, free access to your account history, error resolution rights and limits on your liability for unauthorized transactions, especially if you report them quickly.
- Lost or stolen card: call the issuer right away so it can block the card and send a replacement.
- Deposit insurance: funds may qualify for FDIC or NCUA pass-through insurance when the program is set up that way and your card is registered in your name.
- Privacy: the card company processes your transactions, not your employer. The provider's privacy notice explains what account information, if any, is shared with the employer.
Why Hasn't My Pay Appeared on My Payroll Card?
Deposits normally follow your employer's regular payday, but a holiday or a late payroll submission can push them back. If your pay is missing, check these first:
- The card has been activated and registered
- You were recently enrolled and the first deposit is still being set up
- Your employer changed payroll providers or card programs
- The pay date fell on a weekend or bank holiday
Then compare the deposit with your pay stub and contact payroll with the pay date and amount if it still has not arrived.
Do You Still Get a Pay Stub With a Payroll Card?
Yes and you should keep it. The card only shows how much arrived. The stub shows how that number was calculated: gross pay, each tax, each deduction and the net pay that was loaded onto the card.
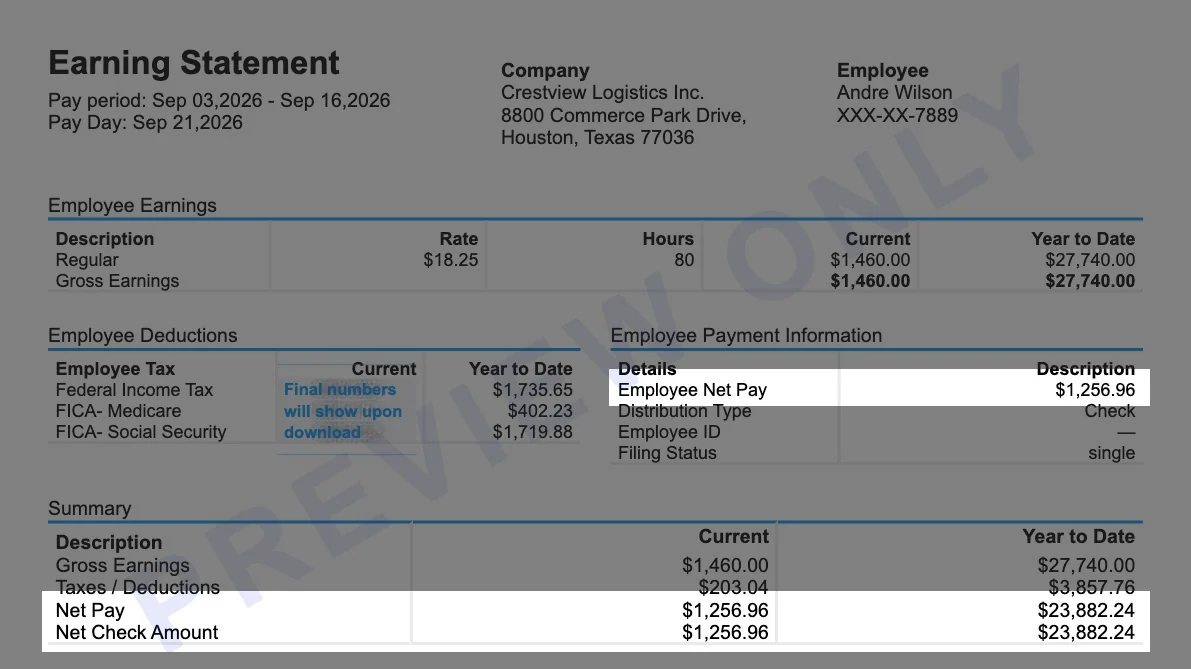
In the sample above, $1,460.00 of gross pay minus $203.04 in taxes leaves $1,256.96 of net pay, which is exactly what should appear on the card. If the card deposit is lower, the stub is your evidence. The year-to-date totals on the stub also match what will appear on your W-2, which matters at tax time and when a landlord or lender asks for proof of income.
What Happens to Your Payroll Card When You Leave Your Job?
Money already on the card is yours. After your last paycheck, check whether the card stays active, whether new fees apply and how long the account remains open. Many people simply move the remaining balance to a bank account or withdraw it in full so an inactivity or maintenance fee cannot eat into it.
Payroll Card Pros and Cons
| Pros | Cons |
|---|---|
| No bank account needed | Fees for some ATM and transfer transactions |
| Pay arrives electronically on payday | Fee-free ATM network may be limited |
| Works for purchases, online shopping and bills | Daily withdrawal limits |
| Safer than carrying cash or an uncashed check | Features differ from one program to another |
| Federal Regulation E protections apply | Less flexible than a full checking account |
Paid on a payroll card? Keep a clear record of every paycheck with a professional pay stub.
Create a Pay Stub Now